Unraveling Tiered Reward Mechanisms in Virtual Card Retention Programs
Greta Albrecht · Aug 26, 2026
Unraveling Tiered Reward Mechanisms in Virtual Card Retention Programs
Virtual card networks operate through digital payment platforms that issue temporary or reusable card numbers for secure transactions, and these systems incorporate tiered reward algorithms to encourage ongoing user activity. Data from industry reports shows these algorithms segment users based on spending patterns, transaction frequency, and account longevity, then assign benefits like increased cashback rates or fee reductions at higher levels. Researchers have documented how such structures emerged prominently in the early 2020s as fintech firms sought to differentiate their offerings amid growing competition from traditional banks and emerging digital wallets.
Core Components of Tiered Structures
Tiered systems typically feature multiple levels, often labeled bronze through platinum or similar designations, where progression depends on cumulative metrics tracked in real time by backend algorithms. These algorithms process variables including average transaction size, geographic diversity of spending, and consistency across months, then calculate eligibility using weighted scoring models that prioritize retention signals over one-time volume. According to analyses from the Federal Reserve Bank of New York, networks adjust thresholds seasonally to align with consumer behavior shifts, and figures from 2025 indicate average retention lifts of 18 to 25 percent among users who reach mid-tier status within the first six months.
Observers note that personalization forms a key layer, with machine learning models predicting churn risk and dynamically offering micro-rewards to nudge users upward. For instance, one European payment processor implemented a system that cross-references user data with broader economic indicators, then modifies reward multipliers accordingly, and this approach has been replicated across platforms in Asia-Pacific markets since late 2024.
Algorithmic Logic and Data Inputs
The underlying algorithms rely on decision trees combined with reinforcement learning loops that refine predictions based on historical cohort performance. Inputs range from basic transaction logs to more advanced signals such as device usage patterns and interaction with reward dashboards, allowing networks to forecast lifetime value and allocate incentives efficiently. A study published by the University of Toronto's Rotman School of Management examined datasets from multiple virtual card providers and found that models incorporating at least seven distinct behavioral variables achieved higher accuracy in identifying at-risk users compared to simpler frequency-based rules.
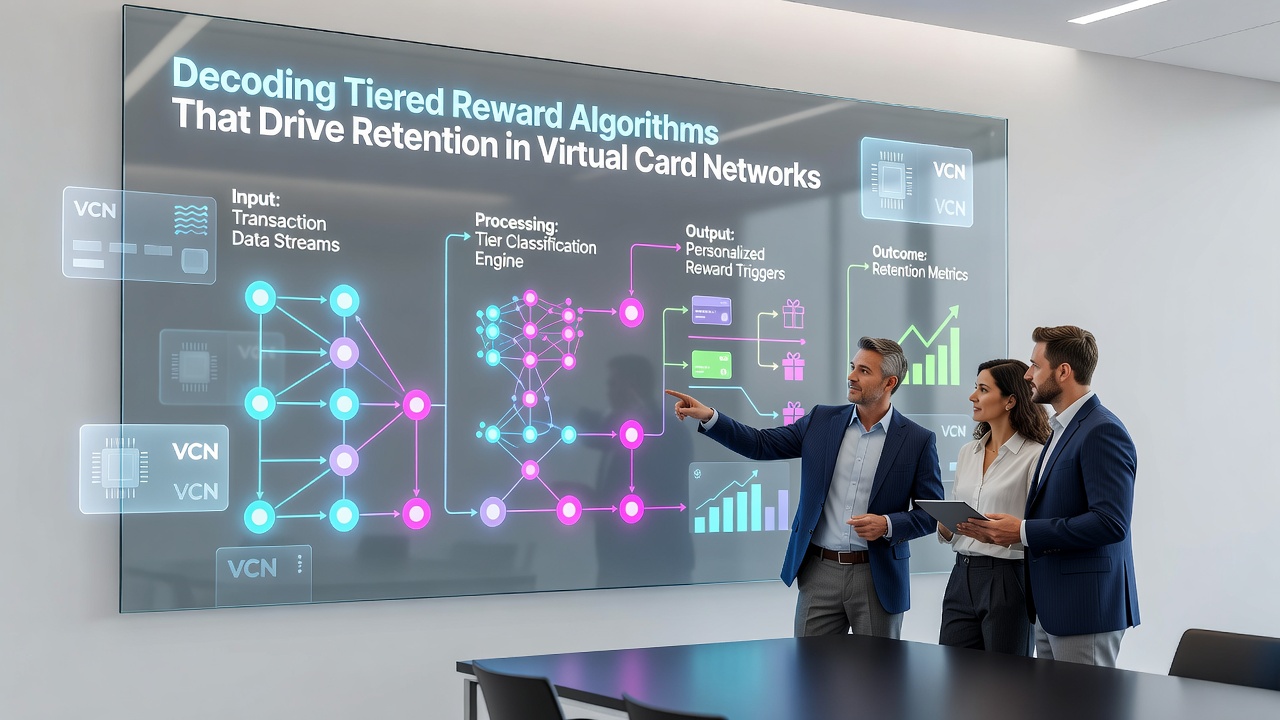
Updates to these systems often occur quarterly, and reports indicate several major networks rolled out enhanced versions in August 2026 that integrated real-time inflation adjustments into reward calculations. This change addressed user feedback on purchasing power erosion while maintaining network profitability margins. Those who have reviewed the technical documentation highlight how the new parameters reduce false positives in tier demotions, thereby stabilizing engagement metrics across diverse user segments.
Regional Variations and Regulatory Context
Implementation differs by jurisdiction, with North American platforms emphasizing cashback tiers tied to merchant categories, whereas Australian providers focus on subscription-style benefits at premium levels. The Australian Securities and Investments Commission has issued guidance on transparency requirements for algorithmic reward disclosures, requiring networks to publish clear criteria for tier advancement. In parallel, Canadian regulatory filings reveal that virtual card issuers must report retention statistics annually, and aggregated data through 2025 shows consistent correlations between tier depth and reduced account closure rates.
Industry associations such as the Electronic Transactions Association have compiled benchmarks that compare algorithm performance across providers, noting that hybrid models blending rule-based and AI-driven elements tend to outperform purely static frameworks. Users in these networks often progress through tiers within three to nine months, after which retention curves flatten unless additional personalization layers activate.
Observed Outcomes Across Networks
Case examples illustrate the mechanics in action. One mid-sized virtual card operator in the United States reported that introducing a five-tier ladder increased repeat transaction rates by 31 percent within the initial rollout year, according to internal metrics shared with research partners. Another provider operating across EU member states documented similar patterns, attributing gains to algorithm tweaks that rewarded cross-border spending more generously during peak travel periods.
What's notable is how these algorithms balance short-term incentives with long-term loyalty signals, using cohort analysis to prevent over-distribution of rewards that could erode margins. Data indicates that networks maintaining transparent communication about progression criteria experience lower complaint volumes and sustained participation rates through the later stages of the user lifecycle.
Conclusion
Tiered reward algorithms in virtual card networks continue to evolve through iterative refinements informed by expanding datasets and shifting regulatory expectations. Evidence from multiple regions demonstrates their role in shaping user behavior, with measurable impacts on retention when calibrated effectively. As platforms incorporate additional data streams and refine predictive capabilities, the structures are expected to grow more sophisticated while remaining anchored in observable transaction and engagement patterns.